Texas Insurance Basics for Smart Policyholders
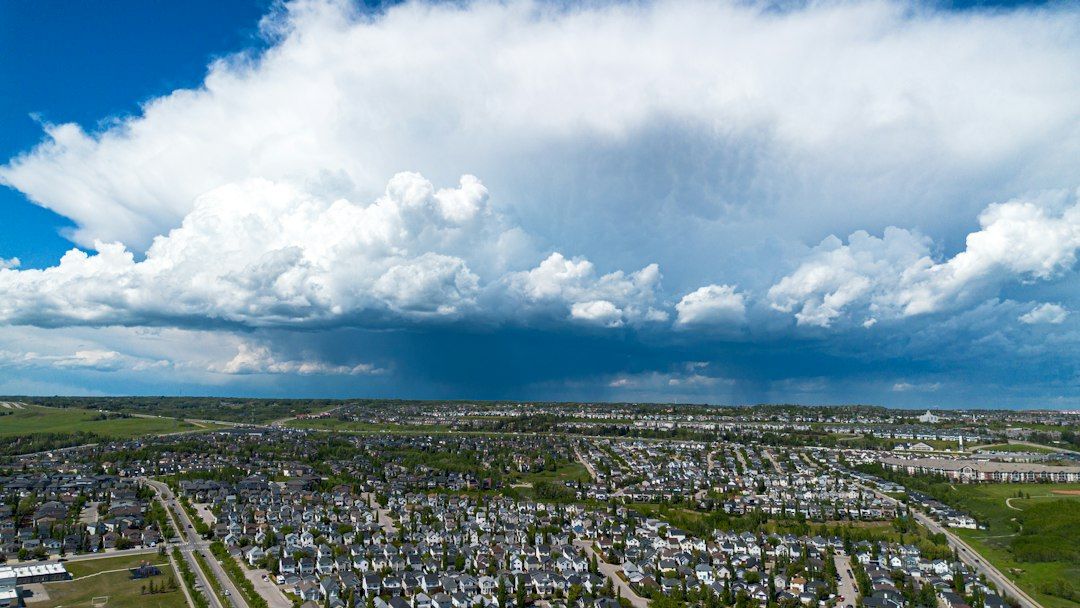
If you live in Texas, you already know that storms, traffic, and a booming housing market can make insurance decisions feel overwhelming. According to the Texas Department of Insurance, hail claims alone cost Texans more than $2.6 billion in 2022.
Introduction
If you live in Texas, you already know that storms, traffic, and a booming housing market can make insurance decisions feel overwhelming. According to the Texas Department of Insurance, hail claims alone cost Texans more than $2.6 billion in 2022. I have spent more than a decade helping families and small businesses protect what matters, and I can tell you the right coverage is neither one size fits all nor overly complicated once you know the essentials. Below, I explain the key policies most Texans need, how rates are set, and the simple steps that can save you money while still keeping you fully protected.
Why Insurance Works Differently in Texas
Texas is a “file and use” state. Carriers can introduce new rates first and justify them later, which means premiums shift faster here than in many other states. In 2023, the Insurance Information Institute reported an average homeowner premium of $2,919 in Texas, nearly 50 percent higher than the national average. Extreme weather, rapid population growth, and rising repair costs all play a role.
Key market trends:
- Weather volatility: The National Weather Service counted 132 confirmed tornadoes across Texas in 2022, the most of any state.
- Urban expansion: More than 1,000 people move to Texas each day (U.S. Census Bureau), increasing claim volume and traffic congestion.
- Construction inflation: Lumber prices have settled since the 2021 peak but remain about 20 percent above 2019 levels, raising home replacement costs. Understanding these pressures helps explain why an annual policy review is vital. A rate that was competitive two years ago might be overpriced today, or worse, your coverage limits might no longer match rising rebuilding costs.
Must-Have Coverage and Cost Drivers
1. Auto Insurance
Texas law requires Bodily Injury and Property Damage Liability, but comprehensive protection usually means adding:
- Personal Injury Protection (covers medical bills regardless of fault)
- Uninsured/Underinsured Motorist (one in eight Texas drivers is uninsured according to TDI)
- Comprehensive and Collision (protects against hail, theft, and accidents) Case example: Maria in Fort Worth saved $430 per year by raising her collision deductible from $500 to $1,000 and bundling auto with homeowners. Her liability limits stayed at 100/300/100, well above the state minimum, which protected her assets after a $78,000 at-fault accident.
2. Homeowners Insurance
Beyond dwelling coverage, look for:
- Extended Replacement Cost (20 percent cushion if rebuild costs surge)
- Water Backup (covers damage from clogged drains, not just sudden pipe bursts)
- Roof Settlement Type (Actual Cash Value can cost thousands after hail; Replacement Cost pays the full amount) Data point: The average hail claim in Texas is $11,200 (Verisk Analytics). Policies with Replacement Cost on roofs often pay double what ACV policies pay.
3. Life and Disability
Life insurance premiums in Texas are among the lowest nationwide thanks to competitive carriers and younger demographics. A healthy 35-year-old can secure a $500,000 20-year term for roughly $27 per month (Policygenius survey 2024). Adding an inexpensive disability rider safeguards income if illness strikes.
Insider Insights and Money-Saving Tips
- Shop your policy every 18 months. Because Texas rates change rapidly, many carriers introduce new discounts for telematics (driving apps) or smart home devices that older policies miss.
- Strengthen your roof for credits. Upgrading to impact-resistant Class 4 shingles can earn an average 15 percent premium discount and reduce future claims.
- Combine policies wisely. Bundling typically shaves 20 percent off combined premiums, but always compare the bundle against standalone quotes.
- Keep credit clean. Texas allows insurers to use credit-based insurance scores. According to FICO, drivers with good credit pay up to 24 percent less on auto premiums.
- Document everything. Photos of home upgrades or jewelry appraisals speed up claims and eliminate adjuster disputes. Looking ahead, I expect more carriers to offer parametric storm coverage. Instead of paying for damage after a storm, these policies pay a fixed amount once wind speeds or hail sizes exceed a preset threshold. Early trials in Florida show payouts within 72 hours, a model that could benefit storm-prone Texas by 2026.
Wrapping Up
Insurance may feel like another bill, but it is truly a financial safety net tailored to your life. In Texas, fast-moving weather and market shifts make regular policy checkups essential. Start by verifying that your auto liability, home replacement cost, and life insurance amounts still match your current assets and family needs. Small adjustments today can prevent large out-of-pocket shocks tomorrow. If you are unsure where to begin, a conversation with a trusted local agent can reveal hidden discounts and coverage gaps in less than an hour.
Kody Amos Agency
At Kody Amos Agency, we treat every policy review like a financial wellness checkup. Our team lives right here in Texas, so we understand the hailstorms, the flood zones, and the highways you drive every day. Whether you need a fresh auto quote, a detailed home replacement cost analysis, or guidance on protecting your family’s income, we take the time to explain options in plain language and shop our network of top-rated carriers for you. Call, click, or visit our office for a no-pressure review, and see why our clients stay with us long after the paperwork is signed. We look forward to helping you safeguard what matters most.
By Kody Amos & Team